Select a picture to open it at full size.
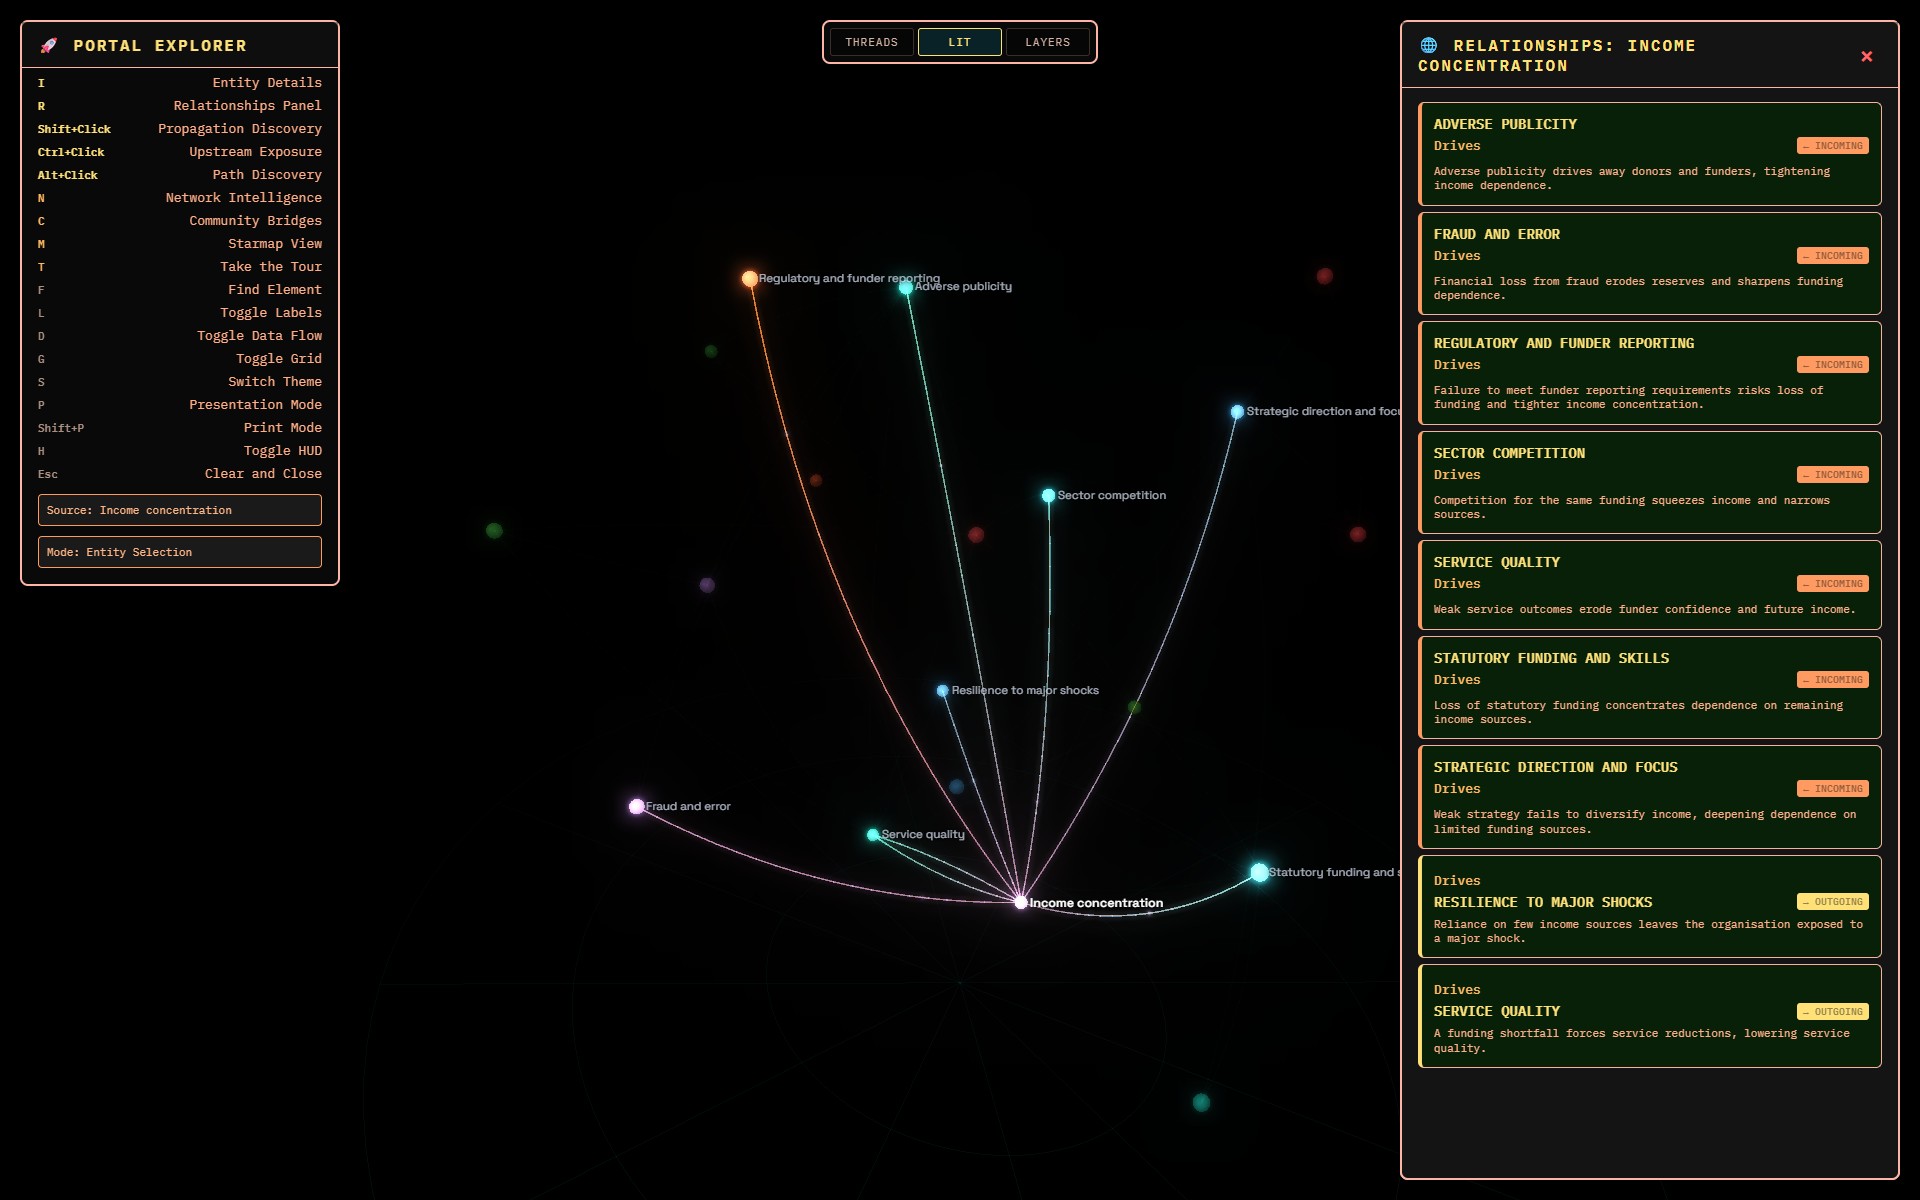
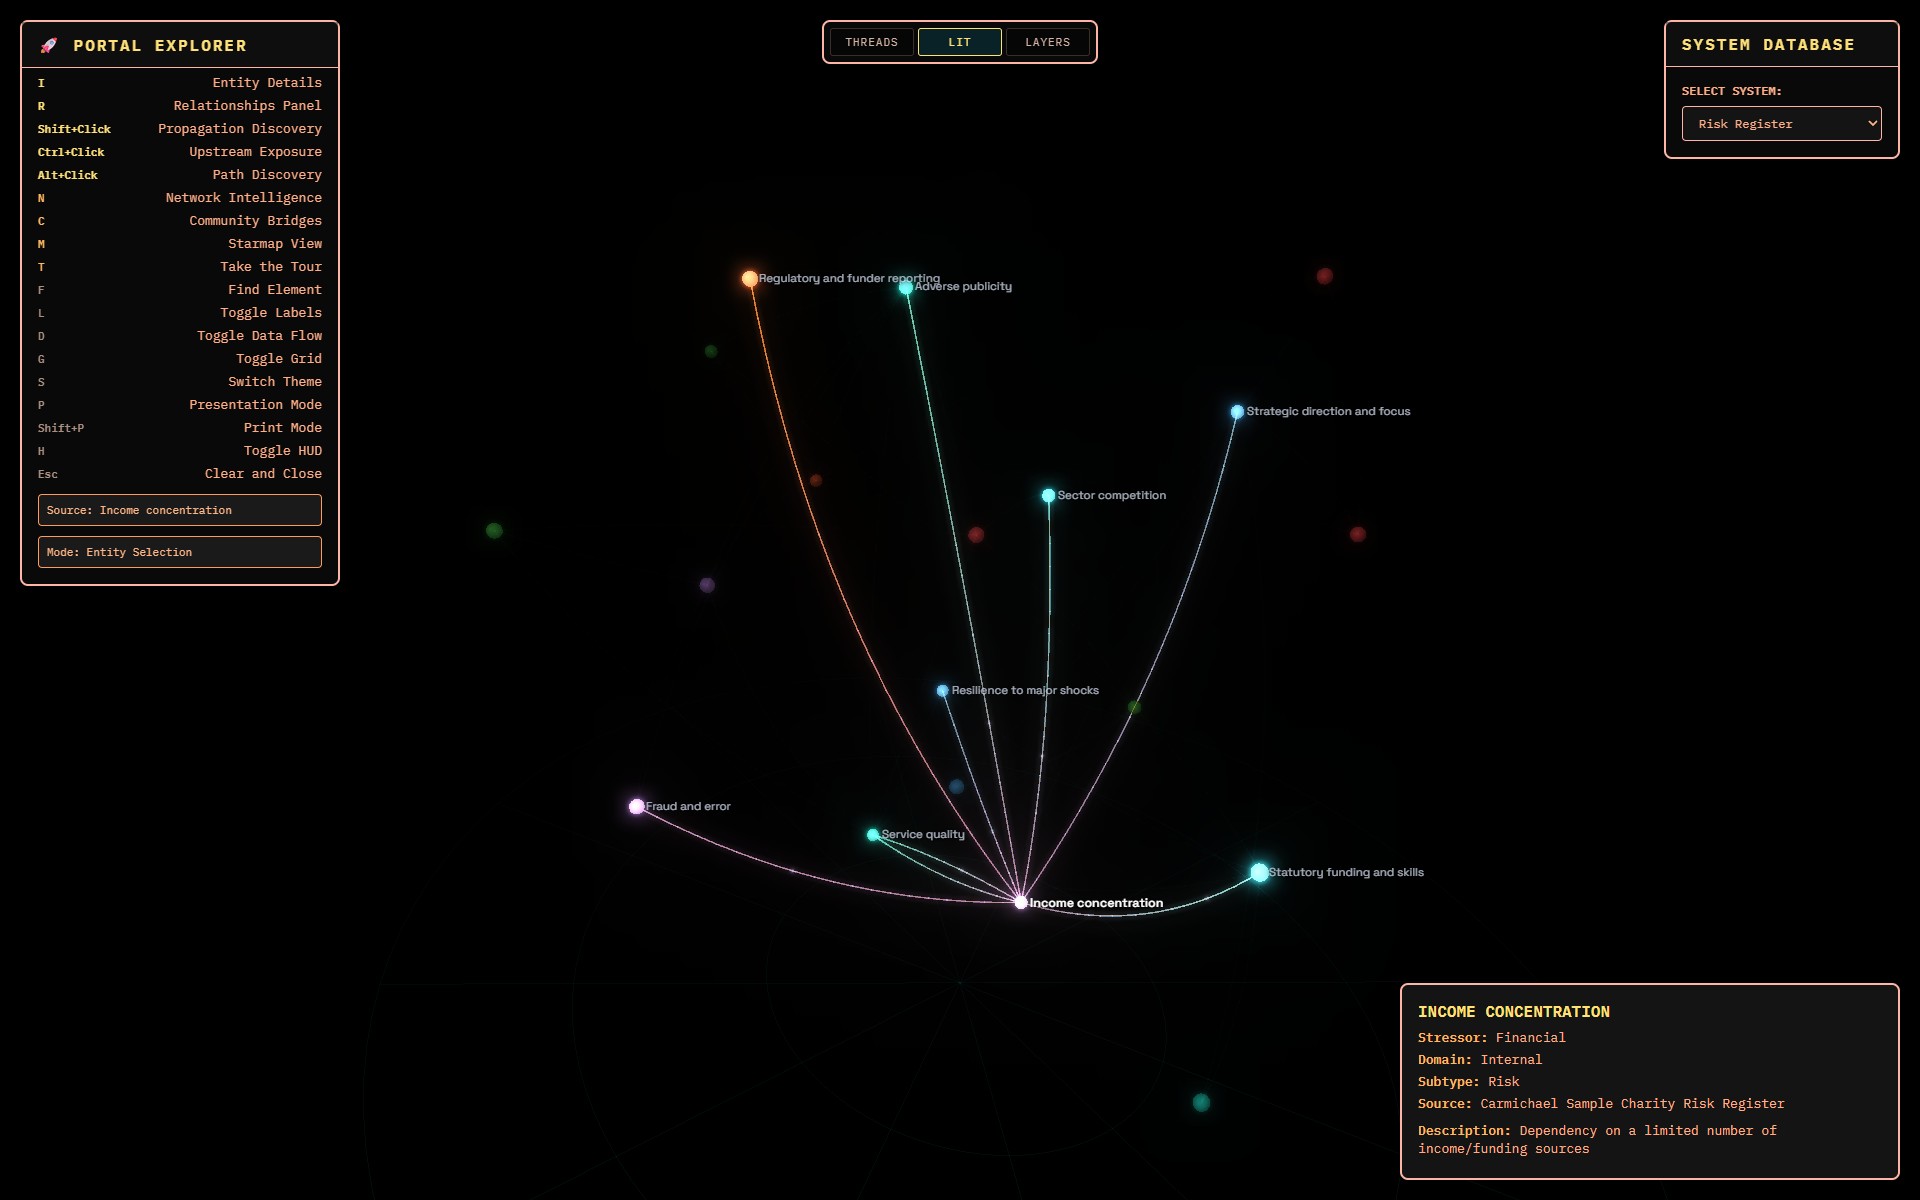
On a risk register, Income concentration is one row in the Financial category: the charity's dependence on a limited number of funding sources.
In the network, seven of the other eighteen risks drive it:
- Strategic direction and focus
- Regulatory and funder reporting
- Fraud and error
- Statutory funding and skills
- Sector competition
- Adverse publicity
- Service quality
The register reports each of those on a separate line. The structure shows them converging on one risk.
Each connection is a written claim with its reasoning. Two examples: “Weak strategy fails to diversify income, deepening dependence on limited funding sources.” “Adverse publicity drives away donors and funders, tightening income dependence.”
A written description of a relationship can be challenged. An undocumented assumption cannot. So the people who own the risks can review the model line by line.
Seen in: Risk Register: nineteen risks based on Carmichael's published sample charity risk register. The 42 connections are Risk Portal's own.
To see it, ask us for a guest login.
A guest login lets you explore the demonstration models yourself.
Ask for a guest loginNext finding
Separate failures converge
When two different systems fail, do they hit the same services?
Read